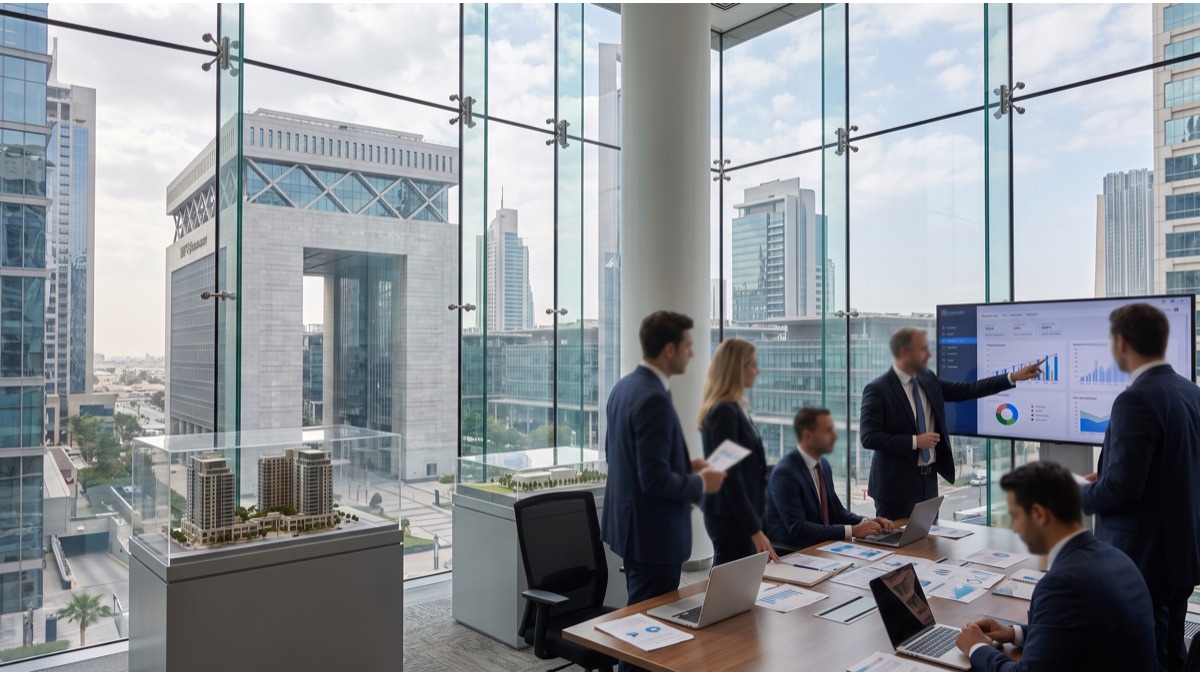
Walk from a government office in ordinary Dubai into the DIFC and, legally speaking, you have effectively crossed a border. The Dubai International Financial Centre operates under its own body of civil and commercial law, adjudicated by its own courts, in English, following English common law principles rather than the UAE's civil law system used everywhere else in the emirate.
That is a genuinely unusual arrangement for a jurisdiction to create for itself deliberately, and understanding why Dubai built it, and how it actually functions day to day, explains a great deal about how the emirate turned itself into a serious regional and global financial hub within roughly two decades.
Why Dubai Wanted a Legal Island for Finance
In the early 2000s, Dubai's leadership set out to build a financial center capable of attracting major international banks, asset managers, and insurers, and quickly ran into a structural obstacle: most global financial institutions and the lawyers who serve them are trained in and most comfortable operating under English common law, the legal tradition underpinning London, New York, Singapore, and Hong Kong as financial centers.
The UAE's mainland legal system, like that of most of the Arab world, is a civil law system with different foundational principles, procedures, and case-law traditions. Rather than ask the entire country to change its legal system, or ask every international bank to adapt to an unfamiliar framework, Dubai's government took the more surgical option of carving out a defined physical and legal zone that would operate under an imported, purpose-built common law framework instead.
This kind of legal engineering is genuinely rare among sovereign states, since most jurisdictions either operate one consistent legal system nationwide or, where multiple systems coexist, arrived at that arrangement through a long colonial or federal history rather than a single deliberate policy decision made within a matter of a few years. Dubai's approach was closer to importing a legal operating system wholesale into a purpose-built zone, treating law itself as a piece of economic infrastructure to be designed for a specific market rather than inherited passively from history.
What the DIFC Actually Is
The Dubai International Financial Centre is a financial free zone established in the mid-2000s, occupying a defined physical district in central Dubai, home today to thousands of registered companies ranging from major global banks and asset managers to boutique law firms, fintech startups, and family offices.
Legally, it is established by federal and Dubai law as a distinct jurisdiction with its own civil and commercial legislation, its own regulator, and its own court system, all operating in English, while remaining fully part of the UAE and Dubai for matters of sovereignty, security, and federal law. It is best understood as a specially chartered legal enclave rather than a separate country.
How the DIFC's Legal System Differs From Onshore Dubai
Companies and individuals operating within the DIFC are generally governed by DIFC laws for civil and commercial matters, a body of legislation deliberately modeled closely on English common law principles and, in places, directly adapted from English statutes, covering areas including companies, contracts, employment, insolvency, trusts, and data protection.
Criminal law, immigration, and most matters touching the wider federal and Dubai government continue to apply within the DIFC just as they do elsewhere in the emirate; what is genuinely distinct is specifically the civil and commercial legal framework governing business activity and disputes between commercial parties operating inside the zone.
How the DIFC Courts Actually Work
Disputes arising within the DIFC are generally heard by the DIFC Courts, an independent common law court system operating entirely in English, staffed substantially by judges with backgrounds in major common law jurisdictions including England, Singapore, and other Commonwealth systems, applying case-law reasoning and precedent in a manner unfamiliar to the UAE's onshore civil courts.
Parties outside the DIFC can, in certain circumstances, also elect to have their contracts and disputes governed by DIFC law and heard in the DIFC Courts, a feature that has made the jurisdiction attractive well beyond companies physically registered within the zone itself, since it offers a genuinely familiar common law forum within the wider Gulf region.
The DIFC Courts have also built a reputation for enforcing judgments efficiently through cooperation arrangements with courts in other jurisdictions, and for offering mechanisms such as a dedicated small claims tribunal for lower-value commercial disputes, features that international counterparties evaluating whether to contract under DIFC law weigh heavily against the alternative of litigating in a less familiar civil law forum elsewhere in the region.
Who Regulates Financial Firms Inside the Zone
Financial services activity within the DIFC is regulated by the Dubai Financial Services Authority, an independent regulator created specifically for the zone and modeled on international best practice from established financial regulators, entirely separate from the UAE Central Bank, which regulates conventional banking activity onshore elsewhere in the country.
This separation allows the DFSA to apply regulatory standards closely aligned with those recognized by international financial institutions and their home regulators, which has been a significant factor in convincing major global banks and asset managers that operating a DIFC-licensed entity carries genuine regulatory credibility recognized by counterparties worldwide.
Why 100% Foreign Ownership Actually Matters
Historically, many categories of business operating in the UAE outside designated free zones required a UAE national shareholder or local service agent holding a defined stake, a structure that many international financial institutions found unattractive for a business built around proprietary capital, client relationships, and regulatory accountability.
The DIFC, like the UAE's other free zones, permits qualifying companies full foreign ownership without a mandatory local partner, giving international firms complete control over their local entity's governance, capital, and strategic direction, a structural feature that proved decisive for many institutions deciding where in the region to locate a genuinely substantive regional headquarters rather than a minimal representative office.
What Kinds of Firms Actually Locate There
The DIFC's tenant base spans large international banks running regional trading and wealth management operations, global and regional asset managers, insurance and reinsurance companies, private equity and venture capital firms, professional services firms including major international law and accounting practices, and a growing cluster of fintech companies drawn by dedicated innovation licensing programs.
Family offices and wealth management structures have also become an increasingly significant part of the DIFC's tenant base in recent years, reflecting a wider regional and global trend of wealthy families establishing formal governance structures for multigenerational assets in jurisdictions offering legal predictability, English-language courts, and internationally recognizable regulatory oversight.
This diversity of tenants is itself a deliberate outcome of how the zone was positioned rather than an accident of organic growth. Early DIFC policy specifically targeted anchor tenants among the largest global banks and insurers first, on the theory that their presence would signal credibility to the smaller specialist firms, law practices, and service providers that would inevitably want to cluster near major institutional clients, a sequencing strategy that mirrors how established financial centres historically developed their own critical mass over far longer timeframes.
How Employment and Data Rules Work Inside the DIFC
Employment within the DIFC is governed by its own employment law rather than the UAE's onshore labor law, covering matters including termination, end-of-service benefits, and working conditions under a framework drafted specifically for the zone's professional and financial services workforce, distinct in various technical respects from the equivalent onshore rules.
Data protection within the DIFC likewise operates under its own dedicated data protection law, drafted with reference to international standards including European data protection frameworks, which matters considerably to international financial institutions subject to strict data governance obligations in their home jurisdictions and seeking assurance that a Dubai operation can meet comparable standards.
Why the Physical Campus Looks the Way It Does
The DIFC occupies a compact, deliberately walkable district featuring the distinctive Gate Building as its architectural centerpiece, surrounded by office towers, a growing retail and hospitality precinct, and an increasing amount of public art and cultural programming, reflecting a deliberate strategy of building a genuine daytime and evening district rather than a purely functional office park.
This physical concentration serves a practical purpose beyond aesthetics: clustering banks, law firms, regulators, and courts within walking distance of one another mirrors the physical density of established financial districts like the City of London or Manhattan's Financial District, a pattern that professionals in the sector consistently describe as genuinely valuable for the informal relationship-building that underpins much financial services business.
How This Compares to Other Global Financial Free Zones
The DIFC is often discussed alongside a small number of comparable jurisdictions that similarly carve out a distinct common law commercial framework within a civil law country, including the Astana International Financial Centre in Kazakhstan and, in a somewhat different form, various financial free zones established elsewhere in the Gulf and wider region in the years since the DIFC's own establishment.
Within the Gulf specifically, the DIFC is frequently compared with Abu Dhabi Global Market, a similarly structured common law financial free zone established roughly a decade later, with the two now competing for many of the same categories of international financial institutions considering a UAE base, each emphasizing slightly different regulatory and strategic positioning.
What Critics Actually Argue
Critics of jurisdictions structured like the DIFC sometimes raise concerns common to international financial centers generally, including questions about the effectiveness of anti-money-laundering enforcement relative to the volume and complexity of capital flowing through such hubs, and the broader debate about whether concentrated financial free zones effectively compete with, or drain activity from, less specialized onshore commercial districts.
Proponents respond that a well-regulated, internationally credible financial centre with strong rule-of-law guarantees, transparent courts, and a recognized independent regulator is a net positive for a national economy, attracting capital, expertise, and employment that would otherwise likely locate in a rival regional hub entirely outside the country, and point to the DFSA's participation in international regulatory cooperation frameworks as evidence of genuine oversight.
How a Company Actually Gets Set Up There
Setting up within the DIFC typically involves selecting an appropriate legal structure, whether a standard limited company, a branch of a foreign company, or a specialized structure for funds or family offices, followed by an application process managed jointly by the DIFC Authority for company registration and the DFSA for regulated financial activities requiring a specific license.
The process is generally understood within the professional services community operating in Dubai to be more standardized and predictable than equivalent onshore company formation, reflecting the zone's deliberate design as a one-stop jurisdiction where registration, licensing, immigration support for employees, and access to courts are all coordinated under a single administrative umbrella built specifically around the needs of financial and professional services businesses.
Where the DIFC Is Expanding Next
The zone has continued to expand its physical footprint and its regulatory scope over the past decade, adding dedicated innovation and fintech licensing hubs, expanding real estate to accommodate continued tenant growth, and broadening the categories of professional and wealth-management activity it actively courts as it positions itself for the coming decades of regional and global capital flows.
Dubai's wider economic diversification strategy continues to treat the DIFC as a central pillar of its ambition to be recognized not merely as a regional trade and tourism hub but as a genuine global financial centre standing alongside London, New York, Singapore, and Hong Kong, an ambition that depends heavily on the continued credibility of exactly the legal and regulatory architecture the DIFC was built to provide.
The model has also proven exportable in a way that reflects well on its original design. Other jurisdictions in the region and beyond have studied the DIFC closely when designing their own financial free zones, borrowing elements of its independent regulator structure, its imported common law framework, and its emphasis on a physically concentrated district rather than a dispersed licensing regime, treating Dubai's experiment as a genuine template rather than a one-off curiosity specific to the emirate's particular circumstances.
For ordinary residents of Dubai who never set foot inside a DIFC-registered company, the practical significance is mostly indirect: the jobs, tax revenue, and international prestige generated by a credible financial centre feed into the wider economy and the emirate's global standing, even though the legal machinery producing those benefits is deliberately invisible to almost everyone outside the specific professional and financial services community operating within the zone's boundaries.
What makes the DIFC worth understanding is that it demonstrates a specific and replicable strategy for a rapidly developing economy seeking global financial credibility: rather than attempting the far slower and more contentious task of reforming an entire national legal system, carve out a defined zone, import a trusted and internationally recognized legal framework wholesale, and let that zone compete directly with the world's other established financial centres on terms international capital already understands.